On a brisk Thursday evening in October, I sat down at our dining table with our household budget ledger and our monthly utility invoices.
My husband Marcus and I had been married for seven years, during which I worked as a pediatric clinic office manager while Marcus worked as an estimator for an architectural millwork firm.
For five years, we had lived frugally, packing our lunches and postponing vacations, to build an emergency liquid reserve fund in a dedicated certificates of deposit account at Oak River Credit Union.
That emergency reserve contained eighteen thousand four hundred dollars, specifically reserved to protect our family if either of us faced medical emergencies, employment layoffs, or major home structural repairs.
Marcus had always known how vital that fund was to my peace of mind, because my childhood had been defined by sudden financial instability and utility shut-offs.
However, Marcus had an older brother named Toby who lived in a perpetual cycle of speculative entrepreneurial schemes and catastrophic financial collapses.
Over the past decade, Toby had started and abandoned an organic juice franchise, an imported tire distributorship, and a specialty mobile car detailing van, each venture leaving behind unpaid suppliers and angry creditors.
Six months earlier, Toby had announced that he was launching a gourmet smoked barbecue food truck called Smokepit Express, purchasing a used commercial trailer that required extensive mechanical and kitchen retrofits.
Marcus had repeatedly lent Toby minor personal loans of three hundred or five hundred dollars over the years, which Toby never repaid, but Marcus always rationalized the handouts as fraternal loyalty.
Three weeks prior, Toby had approached Marcus at our Sunday dinner, begging for twenty thousand dollars to install commercial ventilation hoods and pass municipal health inspection.
I had looked Toby in the eye and told him with absolute firmness that our emergency reserve was untouchable and that we would never cosign or finance his food truck.
Marcus had nodded in agreement beside me, assuring me later that night that he understood the boundary and would never put our household stability at risk.
Before Marcus and I married, we sat down in my small rented apartment and wrote out our shared financial principles in a blue spiral notebook.
We agreed that every dollar of our joint savings would represent mutual security, requiring full transparency and joint consent.
Marcus had seen how his parents suffered through repeated bankruptcies caused by impulsive speculative investments and uncurbed debts.
For seven years, Marcus had been a dependable partner who tracked our mortgage statements and split utility expenses with scrupulous care.
Because our childhoods had been marked by financial hardship, building our emergency reserve was the foundation of our domestic peace.
I wanted to protect our household against unexpected hardship, so I sacrificed restaurant meals and personal shopping without regret.
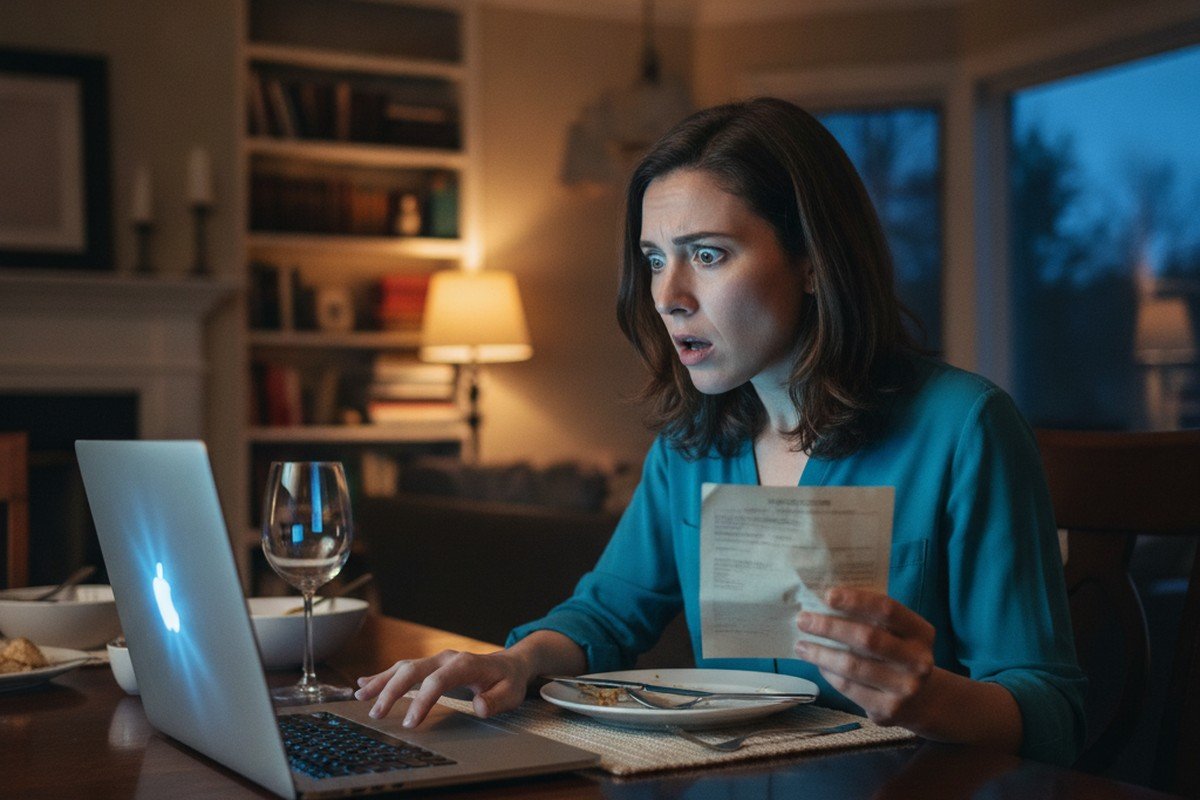
On Thursday evening, I logged into our Oak River Credit Union online banking portal to verify the automatic payment for our annual home insurance renewal premium.
When the account summary dashboard loaded on my screen, I noticed a bright red administrative warning banner pinned across our eighteen-thousand-dollar emergency certificate account.
The certificate of deposit showed a zero available withdrawal balance, and beneath the balance was a bold status alert: “Account Encumbered – Third-Party Commercial Security Pledge.”
I clicked on the electronic correspondence tab and opened the attached PDF legal notification, my pulse pounding in my temples as my eyes scanned the legal clauses.
The document was a formal commercial pledge and collateral agreement executed eight days earlier between Oak River Credit Union and Smokepit Express LLC.
The contract confirmed that Marcus Jenkins had signed a legal guarantee pledging our entire eighteen thousand four hundred dollar joint savings certificate as security collateral for Toby’s commercial equipment installment loan.
Beneath the contract terms was an official credit union notice showing that Toby had missed his first two equipment loan installments, triggering an administrative freeze on our funds.
Attached to the document was an electronic signature verification certificate showing Marcus’s verified IP address, personal social security number, and digital signature.
The paperwork proved that Marcus had quietly visited the downtown credit union branch during his lunch break, used our joint account credentials without my consent, and locked our life savings into Toby’s failing trailer.
I reviewed the legal default clauses in the document, which stated that if Smokepit Express did not bring its installment arrears current within fourteen calendar days, the credit union would execute an irreversible administrative seizure of our certificates.
I sat back in my chair, staring at the glowing laptop screen in stunned silence, feeling completely hollowed out by the depth of Marcus’s deception.
The man who had promised to protect our family had secretly wagered five years of our hard work on his brother’s hopeless barbecue fantasy.
As I stared at the red encumbrance banner on my computer monitor, my trembling hands opened the detailed transaction audit tab.
The audit log revealed that Marcus had authorized the third-party security hold during his lunch break on Wednesday afternoon.
The credit union document confirmed that the commercial pledge was directly tied to a promissory note issued to Smokepit Express LLC.
I compared the certificate account numbers with our tax records, which verified that our entire eighteen-thousand-dollar nest egg was frozen.
The reason this deception felt like an emotional earthquake was that Marcus had looked me in the eye that same evening and smiled.
I realized that while I was carefully budgeting grocery receipts, my husband was quietly staking our life savings on an insolvent food truck.
Just then, the front door opened, and Marcus walked into the hallway, hanging his jacket on the peg and whistling cheerfully as he kicked off his work boots.
He walked into the dining room with a smile, holding a bag of takeout sandwiches, but his smile faltered as he noticed my pale face and the open laptop screen.
“Sarah, what’s wrong? Did something happen with your mother’s test results?” Marcus asked with genuine concern.
“Marcus, look at this screen and tell me why our emergency savings account is locked under a commercial security pledge for Toby’s food truck,” I said, turning the monitor directly toward him.
Marcus froze, his face draining of color as his eyes locked onto the bold red warning banner and his digital signature on the credit agreement.
He set the takeout bag down on the table, swallowed hard, and rubbed the back of his neck with trembling fingers.
“Sarah, listen, please let me explain before you get upset,” Marcus stammered, stepping toward the table with an outstretched hand.
“Upset? Marcus, you took eighteen thousand dollars that we saved dollar by dollar for five years and handed it to a bank to bail out your brother after I explicitly said no!” I said, my voice shaking with cold fury.
“Toby was going to lose his commercial trailer, Sarah! The equipment supplier had a repo crew scheduled to haul away his smoker!” Marcus pleaded. “The loan officer told me it was just an administrative pledge to keep the equipment in place. Toby promised on his honor that his food truck would be profitable by opening weekend!”
“Toby has promised that on every single disaster he has ever run, Marcus!” I retorted. “And you knew I would never agree to this, so you went behind my back, signed a legal encumbrance on our joint money, and hid the paperwork from me!”
Marcus looked down at the floor, attempting to minimize the threat by claiming that the bank wouldn’t actually seize the money if Toby worked out a payment plan.
“Marcus, read paragraph seven of this document!” I shouted, tapping the glass screen. “The credit union has already initiated default proceedings because Toby hasn’t made a single dime in revenue, and our money will be gone in fourteen days!”
When Marcus arrived home, the argument deepened as he tried to defend Toby’s disastrous business history.
“Sarah, Toby has changed, he has spent six months perfecting his hickory smoked brisket recipe!” Marcus argued desperately.
“A recipe does not pay commercial equipment installments, Marcus!” I shouted back, holding the pledge document before his eyes.
“You pledged our future on meat smokers and food truck tires after promising me you would never risk our emergency fund!” I reminded him.
Instead of apologizing, Marcus accused me of lacking compassion for his brother’s lifelong ambition.
That was the moment the confrontation reached its breaking point, because Marcus was choosing his brother’s delusion over our reality.
Then Marcus admitted that Toby had threatened to cut off all family contact if Marcus refused to sign the collateral pledge.
Hearing that admission revealed that Toby had emotionally blackmailed my husband into compromising our marriage.
The reason this breach of trust was so catastrophic was that joint banking certificates cannot be unpledged unilaterally once a commercial borrower falls into formal default.
I believed that if the credit union seized our eighteen thousand dollars, our household would be stripped of all financial protection, leaving us completely vulnerable to any medical or housing emergency.
I feared that Marcus’s inability to establish boundaries with his brother would eventually drag our entire marriage into bankruptcy and financial ruin.
I wanted to protect our household future and enforce total accountability, so I refused to let Marcus hide behind fraternal guilt.
“Tomorrow morning at eight o’clock, you and I are meeting with the credit union commercial branch manager and Toby,” I stated with unyielding resolve.
“Sarah, don’t drag Toby into this, he’s under immense stress trying to prep his menu,” Marcus pleaded, still trying to shield his brother.
“Toby is the one who took our savings hostage, Marcus! You either come to that branch with me, or I am walking into a family law attorney’s office to file for legal separation and freeze every asset we own,” I told him.
The finality in my voice shocked Marcus into absolute silence, making him realize that our marriage was standing on the precipice of collapse.
On Friday morning at half past eight, Marcus and I sat in the executive office of branch vice president Karen Holloway at Oak River Credit Union.
Toby arrived twenty minutes late, wearing stained work jeans and smelling of wood smoke, carrying a battered plastic accordion folder under his arm.
Karen Holloway placed the commercial pledge agreement on her desk and reviewed the default timeline with us, confirming that Smokepit Express was two months delinquent on three thousand six hundred dollars of installment obligations.
Karen explained that under credit union bylaws, the institution was legally required to liquidate the pledged collateral unless the borrower cured the arrears and provided alternative security.
Toby tried to argue, claiming that the city health inspector had delayed his permit unfairly and that he just needed another sixty days of leeway.
I cut him off immediately, leaning across the desk with unwavering authority. “Toby, you are not getting another sixty days of my family’s savings. You knew Marcus used our emergency fund without my consent, and you took advantage of him.”
I opened my portfolio folder and presented Karen with a certified copy of our joint account agreement, which contained a clear clause requiring dual-signature authorization for encumbrances over ten thousand dollars.
Karen reviewed the original signature card and compared it with the electronic single-signature pledge Marcus had executed through the online portal.
Karen’s expression turned serious as she realized that the branch loan officer had bypassed credit union underwriting protocol by accepting Marcus’s sole digital authorization on a joint asset with dual-consent restrictions.
Karen explained that while the pledge was administratively recorded, the procedural defect created substantial liability for the credit union if contested in court.
“Mister Toby Jenkins, here is the reality,” Karen said firmly, turning to Toby. “The credit union cannot maintain a collateral hold on this account without facing immediate legal challenge. You have forty-eight hours to refinance this equipment through a personal guarantor or surrender the commercial smoker trailer to our recovery division.”
Toby stared at Karen in utter disbelief, realizing that his manipulation of Marcus could no longer protect him from reality.
Toby turned to Marcus, begging him to intervene, but Marcus looked at me, saw the absolute boundary in my eyes, and finally shook his head.
“No, Toby. I cannot help you anymore,” Marcus said with quiet sorrow. “I broke my wife’s trust to bail you out, and I almost destroyed my own marriage. You have to handle your own business.”
Hearing Marcus speak those words gave me immense relief, confirming that he had finally broken free from his brother’s toxic financial grip.
On Saturday morning, Toby failed to secure another guarantor and voluntarily surrendered the commercial food truck trailer to the credit union recovery team to extinguish his commercial debt.
Karen Holloway executed an immediate administrative release of our certificate of deposit, restoring the entire eighteen thousand four hundred dollars to our active available balance.
On Monday afternoon, Marcus and I met at the branch to restructure our personal accounts, establishing strict dual-authorization safeguards that require in-person physical signatures for any transfer or pledge over one thousand dollars.
Marcus signed an agreement agreeing to attend financial counseling and open an individual separate account for his discretionary spending, ensuring that our household reserves remain permanently protected.
Toby has refused to speak to either of us since the trailer was repossessed, but Marcus has stood firm, refusing to apologize for choosing his marriage over his brother’s reckless schemes.
Our eighteen-thousand-dollar emergency fund sits safely in our credit union vault, serving as an enduring reminder that true marital trust requires clear boundaries, uncompromising honesty, and shared protection.
During our second counseling session, Marcus brought our original wedding vows and placed them beside our household budget sheets.
He explained that watching Toby fail repeatedly had made him feel like an inadequate brother, which was why he had succumbed to guilt.
I told Marcus that I loved him for his generous heart, but that true love requires boundaries so that compassion does not become self-destruction.
Because we faced the truth together without deceit, our marriage emerged stronger, wiser, and permanently anchored in mutual respect.
I believed that protecting our financial security was an act of profound love that preserved our future for our children.
We reviewed our credit union statements every Saturday morning, confirming that zero unauthorized encumbrances or transfers occurred.
That shared discipline restored the peaceful foundation of our home, proving that true partnership thrives on unwavering accountability.
Three days after Toby surrendered the food truck, Marcus and I attended our first marital financial counseling session.
Marcus sat on the sofa and openly confessed how his childhood fear of family rejection had driven him to enable Toby’s reckless habits.
The counselor helped Marcus understand that true loyalty does not require sacrificing the person you swore to protect.
Over the following six weeks, Marcus took complete ownership of our household bills, reviewing every statement with me at the kitchen table.
The credit union issued an official letter confirming that our certificate of deposit was fully cleared of all legal encumbrances.
Now, our eighteen thousand dollars remains safely invested in our insured reserve, anchoring our home in mutual honesty and earned trust.